
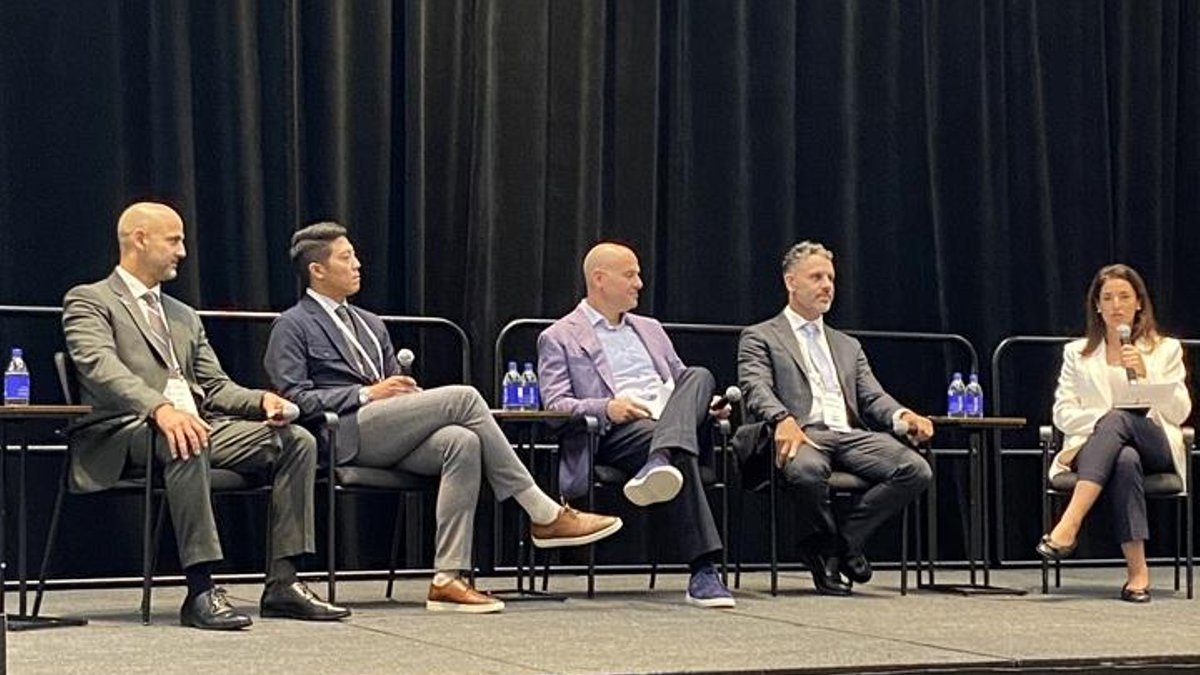
Canadian multifamily real estate is experiencing a notable shift as investors redirect capital from new purpose-built rentals toward older, value-add properties. The transition stems from mounting challenges in the sector, including rising vacancies, declining rents, and stricter financing terms—all of which are unfolding unevenly across key markets.
Industry leaders discussed these trends at the Canadian Apartment Investment Conference in Toronto last month. The downturn in multifamily fundamentals has produced varying outcomes depending on the region, with some markets showing resilience while others face sharp declines in rents, vacancies, and transaction activity.
Toronto: A Focus on Value-Add Strategies
Toronto’s rental market has seen rents dip since 2025 before a modest rebound in early 2026, according to Michael Betsalel, executive vice-president at JLL. Vacancy rates have also declined since the first quarter, while capitalization rates and transaction volumes have increased. This shift signals a return to value-add approaches, particularly in older buildings where land costs are minimal and density can be expanded.
Institutional investors are now acquiring new developments at near-replacement cost, reflecting confidence in sustained demand. “Many Canadian institutions that previously focused on construction are now recognizing the difficulties in that segment,” said Nurit Altman, managing director at RBC Capital Markets. Projects that maximize density on existing sites are proving most effective, leveraging cost efficiencies.
Private capital remains plentiful, but the market has stabilized after a volatile period. The renewed institutional interest in new developments indicates a return to disciplined underwriting, prioritizing financial prudence over speculative expansion.
Montreal: Liquidity Fuels Activity
Montreal’s multifamily sector has seen vacancy rates climb from 1.5% to 2.9% over six months, yet transaction volumes rose 25.4% year-over-year. Cap rates have tightened slightly, showing strong investor demand despite higher vacancies. Thierry Samlal, principal partner at PMML, noted that private investment groups are particularly active, with a focus on succession planning and intergenerational transfers.
Investors are targeting value-add properties and buildings constructed after 2017, prioritizing assets capable of rent increases even as broader market conditions weaken. “The primary driver in our market is the liquidity available to investors,” Samlal explained. The preference for higher-quality assets has created opportunities for buyers willing to invest in older properties with growth potential.
Montreal’s stability contrasts with other regions, where excess supply and policy changes have had a heavier impact. The province’s strong liquidity position continues to attract buyers seeking both stability and growth opportunities.
Related Post: Jakarta hotel market set for H2 growth
Vancouver: Challenges and Opportunities
Vancouver’s multifamily market presents a more difficult environment, with rents falling, vacancies reaching a two-decade high, and transaction volumes down 35% compared to last year. Cap rates have risen, reflecting increased risk. Mark Goodman, principal at Goodman Commercial, observed that demand for large, new purpose-built rentals has nearly disappeared, with investors now focusing on older, smaller wood-frame buildings.
The average sale price for these properties in the first half of 2026 was $9 million for buildings averaging 26 units. The shift away from new construction is partly due to inclusionary zoning policies, which require 20% to 30% of units in new developments to be affordable—a factor Goodman describes as detrimental to profitability. “These policies have made new construction financially unfeasible at current rates,” he stated.
Despite these challenges, Goodman highlighted Vancouver’s current market as an attractive buying opportunity. Property values have dropped 35% to 45% over the past three years, offering a reset for investors in older assets. The question remains whether demand will stabilize or if further declines are likely.
Alberta: Balancing Supply and Demand
Financing continues to rely heavily on Canada Mortgage and Housing Corporation’s multi-family loan programs, which remain the primary source of debt for transactions. Over the past year, there has been a noticeable shift toward equity-driven purchases, as investors seek lower leverage structures.
Older wood-frame apartments are now the preferred asset class in Vancouver, as buyers target properties with renovation potential. The market for new, amenity-rich towers has stalled, redirecting capital toward smaller, more affordable buildings.
Transaction activity has increased despite lower overall deal values, indicating active buying in this segment. Investors focus on properties that can be repositioned through interior upgrades and unit mix adjustments.
Policy constraints continue to influence development decisions, with requirements for below-market units in new projects discouraging large-scale construction. This has reinforced the shift toward existing stock.


